12.11.2026
Foreign companies may carry out both commercial and representative activities in the territory of the Russian Federation.
When a foreign company conducts activities in the territory of the Russian Federation, it is necessary to determine whether such activities give rise to a permanent establishment for tax purposes.
Resolving this issue is necessary for the correct calculation of taxes in the territory of the Russian Federation. The concept of a «permanent establishment» has a special meaning in tax legislation, distinct from the civil law concepts of a «representative office of a legal entity» or a «branch.» This concept, while having no organizational or legal significance, determines the tax status of a foreign company in the Russian Federation.
If the activities of a foreign company create a permanent establishment, it incurs tax obligations in accordance with the legislation of the Russian Federation. Income of a foreign company received through a representative office established in the territory of the Russian Federation is subject to corporate profits tax.
If the activities of a foreign company do not create a permanent establishment in the territory of the Russian Federation, only the company’s income derived from sources in the territory of the Russian Federation is subject to corporate profits tax.
Whether a company is considered to create a permanent establishment depends on what activities are carried out in the territory of the Russian Federation and on the documentary formalization of such activities.
The concept of a «permanent establishment» of a foreign company is established by the Tax Code of the Russian Federation, which provides that, for corporate profits tax purposes, a permanent establishment of a foreign company in the Russian Federation means any separate subdivision or other place of business of the company through which the company regularly carries out business activities in the territory of the Russian Federation related to the sale of goods, construction and installation works, or the provision of services.
An exception is made for activities of a preparatory and auxiliary nature.
The list of activities that may lead to the creation of a permanent establishment in the territory of the Russian Federation is not exhaustive.
The fact that a foreign company carries out preparatory and auxiliary activities in the territory of the Russian Federation, in the absence of the characteristics of a permanent establishment, cannot be regarded as leading to the creation of a permanent establishment.
In practice, it is quite difficult to draw the line between preparatory and auxiliary activities and core business activities.
For example, if a foreign representative office hires sales managers or a foreign trade specialist, this is one of the signs of conducting business activities and processing specific transactions, which may lead to the conclusion that a permanent establishment exists in the Russian Federation for tax purposes.
Also, if a foreign representative office has a warehouse that significantly exceeds what is needed for the presentation of samples, this may indicate the conduct of commercial activities in the territory of the Russian Federation.
There are cases where a foreign company does not officially open a representative office or branch in the territory of the Russian Federation, but in practice conducts commercial activities through specific representatives who are individuals. In such a situation, the tax authorities may conclude that activities are being conducted in the territory of the Russian Federation based on monitoring the websites of parent companies, where the contact details of such representatives are indicated.
Example of a risky operating structure in Russia through a representative office of a foreign company
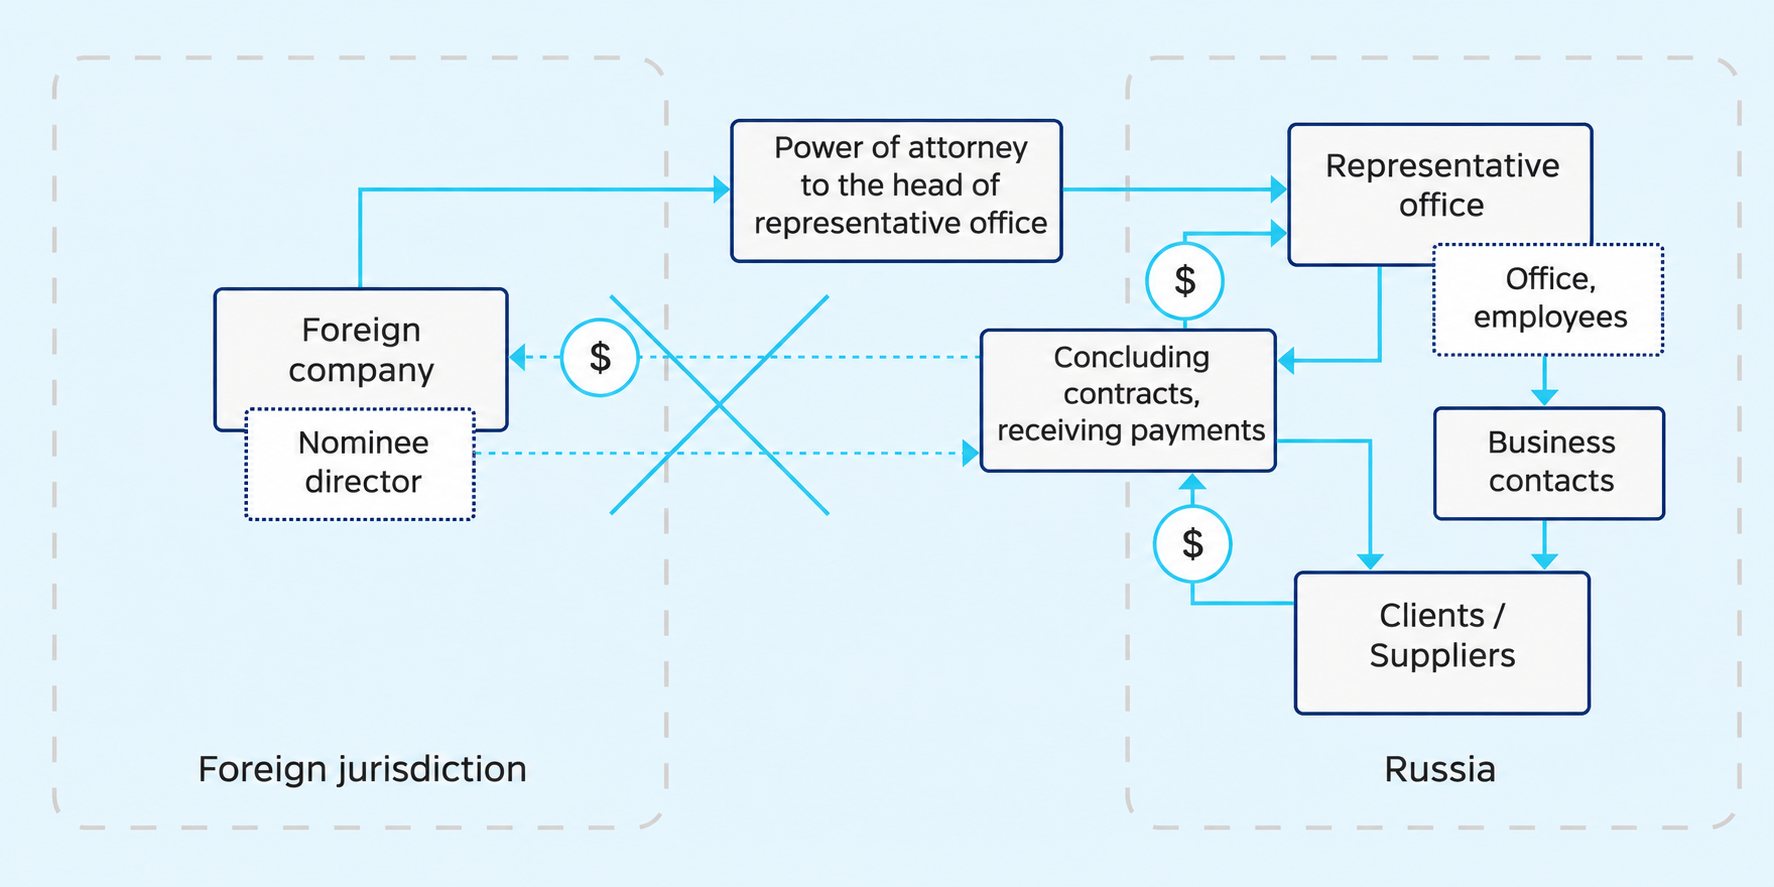
Evidence of the fact that a foreign company conducts business activities in the Russian Federation is based on the following four basic circumstances:
- Entering into contracts with buyers on behalf of the representative office / attorney-in-fact
- Receiving payments from buyers directly into the accounts of the representative office or into the accounts of the foreign company opened with a Russian bank
- Conducting business correspondence with buyers on behalf of the head of the representative office (or other authorized persons of the representative office) / attorney-in-fact
- Actual performance of contracts with buyers by the representative office / attorney-in-fact without involving the resources of the parent company.
In addition, please note that, as of 01.01.2015, amendments regarding the recognition of a foreign company as a tax resident of the Russian Federation entered into force.
For tax purposes, tax residents of the Russian Federation include, among others, foreign organizations whose place of management is the Russian Federation, unless otherwise provided by an international treaty of the Russian Federation on taxation matters.
In our opinion, the overwhelming majority of foreign companies controlled by Russian citizens do not have real places of management outside the Russian Federation, are in fact managed from the territory of the Russian Federation, and therefore may be recognized as tax residents of the Russian Federation in accordance with Article 246.2 of the Tax Code of the Russian Federation.
In our opinion, this provision has serious consequences for the taxation of foreign companies controlled by Russian citizens, not only in relation to corporate profits tax, but also in relation to other taxes (for example, VAT).
Therefore, taking these changes into account, the issue of permanent establishment will only become more significant.